

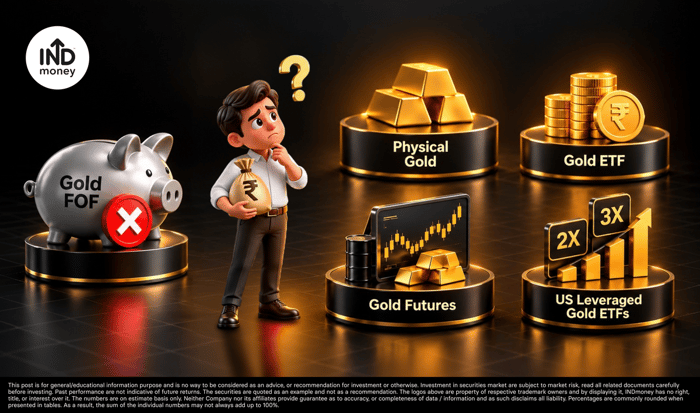
- What Has Stopped, and Can You Still Invest in Gold?
- Will Your Existing Gold Mutual Fund SIP Continue?
- Where Can You Invest Fresh Money in Gold in India?
- Can Indian Investors Invest in US Gold ETFs and Gold Mining Stocks?
- Indian Gold ETF vs US Gold ETF: Which Is More Practical?
- What Should Gold Investors Do Now?
You have ₹50,000 ready to invest in gold. Or perhaps you have decided to start small, putting away ₹5,000 every month. You open your investment app, select a gold mutual fund, and discover that fresh investments are unavailable.
Gold is still being traded. So why can’t you put money into this fund?
The answer lies in the route you selected. Several mutual fund houses have temporarily restricted incoming money into specified gold fund-of-funds, or FoFs. These funds invest in gold ETFs. Purchasing gold ETFs directly on the stock exchange is a separate transaction, and that route remains available.
Can an existing SIP continue? How can a new monthly investment work? And when do Sovereign Gold Bonds (SGBs) or US gold ETFs make sense?
What Has Stopped, and Can You Still Invest in Gold?
Several mutual fund houses restricted new investments in selected gold funds from October 15–16, 2026. HDFC's restriction applies to requests received after 3 pm on October 15, while Nippon India and Tata specify October 16. The affected funds include gold fund-of-funds (FoFs), which invest in gold ETFs, and some gold-and-silver FoFs.
| Transaction | Position in affected schemes |
| Fresh or additional lump sum; switch-in | Not allowed under the notices checked |
| New SIP or STP registration | Not allowed |
| Existing SIP instalment | Usually continues if registered before the deadline |
| SIP top-up or step-up | Some fund houses have stopped increases; check your fund |
| Redemption or switch-out | Still allowed under normal fund rules |
| Direct gold ETF purchase on an exchange | Still available as a separate way to invest |
The notices do not say when fresh investments will reopen. You can still buy and sell gold ETFs directly on the stock exchange.
Not every fund house explains the reason. The World Gold Council says the restrictions followed talks with SEBI and may be meant to reduce gold imports, but the fund house notices do not all confirm this.
gold mutual fund investment restrictions explainer covers why the restrictions happened. Here, we look at what investors can do next.
Will Your Existing Gold Mutual Fund SIP Continue?
An existing ₹5,000 SIP may continue even if you cannot start a new ₹5,000 SIP in the same fund. HDFC, Nippon India, Tata and Axis allow eligible SIPs set up before their deadlines to continue, while restricting new registrations.
If you registered your ₹5,000 SIP before the cutoff, your regular instalments may still go through. The units you already own remain invested, and their value will continue to change with gold prices and fund expenses.
But increasing your SIP may not be allowed. Nippon India specifically restricts step-ups in existing SIPs, while Tata restricts top-ups. Permission to continue your regular SIP does not necessarily mean you can increase it.
Think carefully before cancelling an existing SIP. You may not be able to register it again until the restrictions end. Check the fund's cutoff date, regular SIP amount, planned increases and rules for existing systematic transfer plans (STPs).
You can still redeem your units under normal fund rules. The restriction affects money coming into the fund; it does not change the outlook for gold itself.
Where Can You Invest Fresh Money in Gold in India?
1. Purchase a gold ETF directly on the exchange
If you planned to invest in a gold FoF, a gold ETF is the closest alternative. You buy ETF units directly on the exchange, avoiding the FoF's extra expense layer but placing the order yourself.
You need a demat and trading account with money in it. Search for the ETF during market hours. Nippon India ETF Gold BeES trades as GOLDBEES; HDFC Gold ETF as HDFCGOLD.
To invest ₹5,000 monthly, choose a date and buy whole ETF units within your budget. At ₹125 per unit, ₹5,000 buys 40 units before charges; at ₹128, it buys 39 units for ₹4,992. Keep enough cash for fees.
Some brokers support scheduled ETF orders, but they differ from mutual fund SIPs. An order needs enough funds and an available seller; it may not execute.
Compare the market price with the ETF's indicative net asset value, or iNAV, which estimates the underlying gold value per unit during the day. Make sure the iNAV is current.
If iNAV is ₹125 and the ETF sells for ₹127.50, you pay a 2% premium. If that premium disappears, you could lose money even if gold stays flat.
Check the gap between buy and sell quotes (bid-ask spread), available units and trading activity. A limit order controls the maximum price but may not execute. Add brokerage, exchange charges, taxes and demat-related costs.
How do major Indian gold ETFs compare?
Some figures could not be verified for the same date. Missing figures do not mean a fund has performed badly.
| Gold ETF | 1Y return / 3Y CAGR | Tracking error | AUM | Expense ratio |
| Nippon India ETF Gold BeES | 27.16% / 35.11% | 0.41%, one year | ₹56,981.58 crore | 0.81%, monthly average TER |
| SBI Gold ETF | Not verified for the common date | Not verified | Not verified from the current AMC factsheet | Not verified from the current AMC factsheet |
| HDFC Gold ETF | 27.41% / 35.34% | 0.39%, annualised over the last 12 months | ₹23,899.78 crore | 0.59%, published base expense measure including specified levies* |
| ICICI Prudential Gold ETF | Not verified for the common date | Not verified | Not verified from the current AMC factsheet | Not verified from the current AMC factsheet |
HDFC's one-year tracking error was slightly lower than Gold BeES'. This shows how consistently a fund stays close to its benchmark's daily returns. Lower is usually better for comparable periods and methods, but it does not make gold safer.
Tracking difference shows the gap between a fund's return and its benchmark. HDFC returned 27.41% in one year versus 28.62% for its benchmark, a 1.21 percentage-point gap. Gold BeES reported −1.46%. These gaps include more than the annual fund fee.
Fees, cash holdings and valuation timing can affect returns. A larger ETF is not always cheaper to trade. Paying a 2% premium on ₹1 lakh of underlying value costs ₹2,000 upfront, compared with ₹200 saved in one year by a 0.20 percentage-point lower fee.
2. Check Whether Your Gold Mutual Fund Is Accepting New Investments
A gold fund may still appear in an app even when fresh investments are blocked. An investment button does not guarantee the fund house will accept your money.
On October 15, 2026, HDFC blocked fresh investments, switch-ins and new SIPs in HDFC Gold ETF Fund of Fund and HDFC Gold Silver Passive FOF. Qualifying existing SIPs and redemptions could continue.
For instance, an existing ₹5,000 SIP might continue while a new ₹5,000 SIP in the same fund cannot start.
Before investing, check the latest notice from the fund house. Find out whether it affects new lump-sum investments, extra purchases, new SIPs or increases to an existing SIP.
And what if your preferred gold mutual fund isn't accepting investments?
A gold ETF is one alternative. You can buy it through a demat account, but check its market price against iNAV and allow for trading costs.
Another possibility is a multi-asset allocation fund. But this is not a fund that invests only in gold.
SBI Multi Asset Allocation Fund held 6.42% in SBI Gold ETF on September 30, 2026. A ₹5,000 investment would mean about ₹321 of indirect exposure through that ETF holding, not ₹5,000 in gold.
The rest of the money was invested in other assets, including shares, debt and other holdings. Their performance also affects the fund's returns, and its gold allocation can change.
The distinction matters: if your goal is specifically to add gold, a multi-asset fund is not a direct substitute. It may be worth considering only if you also want exposure to other kinds of investments.
3. Consider existing Sovereign Gold Bonds on an exchange
No fresh SGB issue was open in the RBI records checked for October 27. You may still buy existing listed SGBs if sellers are available. A redemption calendar for old bonds does not signal a new issue.
SGBs follow gold prices and pay interest. The 2023–24 issues pay 2.5% annually on the original issue value, in two instalments, not on the amount you pay to buy them later.
A bond originally issued at ₹5,000 pays ₹125 a year. If you buy it for ₹12,000, your annual interest is about 1.04% of what you paid, before tax. Your final return also depends on the redemption or sale value.
SGBs mature eight years after they were originally issued, not eight years after you buy them. RBI's early redemption option begins after five years, on specified interest payment dates. If you sell on the exchange instead, you need to find a buyer at an acceptable price.
Check the bond's market price, gold-linked value, remaining interest payments and maturity date. It could trade at a premium or discount, and selling may not always be easy.
From April 1, 2026, only individuals who subscribed to an SGB at issue and kept it until maturity can claim the redemption tax exemption. A secondary-market purchase does not qualify for that exemption, even when retained until maturity. Early redemption also does not qualify, and interest is taxable.
4. Use coins or bars when physical ownership is the goal
Coins and bars come with premiums, 3% GST, storage costs and possible deductions on resale. Check purity, keep an invoice and ask about buyback terms. Jewellery also includes making charges, making it less useful for pure gold-price exposure.
Can Indian Investors Invest in US Gold ETFs and Gold Mining Stocks?
Indian investors with access to US markets can explore US-listed gold ETFs and gold mining stocks. But not every investment with gold in its name works the same way.
Some funds hold physical gold, some invest in companies that mine it, while others try to multiply daily price movements. Understanding this difference matters more than simply comparing their past returns.
1. Physical Gold ETFs: GLD, IAU and GLDM
These are the closest alternatives to traditional gold ETFs in India. They hold physical gold through trusts and aim to follow gold prices after deducting expenses.
| US Gold ETF | What Does It Do? | Annual Fee |
| SPDR Gold Shares (GLD) | One of the largest and most actively traded gold-backed products. It tracks the price of physical gold. | 0.40% |
| iShares Gold Trust (IAU) | Offers similar physical gold exposure to GLD, but with a lower annual fee. | 0.25% |
| SPDR Gold MiniShares (GLDM) | Tracks physical gold with a lower annual fee than GLD and IAU. | 0.10% |
All three provide broadly similar gold exposure. The main differences are their annual fees, trading liquidity and the price at which investors can buy or sell their units.
Their returns can still fall when gold prices decline. Indian investors also need to consider USD-INR exchange-rate movements and overseas investing costs.
2. Gold Mining ETFs: GDX and GDXJ
What if, instead of investing in gold, you invest in the companies that produce it?
Gold mining ETFs do exactly that. They invest in shares of mining businesses rather than holding gold bars.
| Gold Mining ETF | What Does It Invest In? | Annual Fee | Additional Risk |
| VanEck Gold Miners ETF (GDX) | A basket of major global gold mining companies. | 0.51% | Mining costs, production problems and stock-market movements can affect returns. |
| VanEck Junior Gold Miners ETF (GDXJ) | Primarily smaller gold and silver mining companies, including some earlier-stage businesses. | 0.52% | Higher exposure to smaller companies, funding difficulties and mine development risks. |
Here is why this difference matters.
Suppose gold prices rise by 10%, but a mining company's fuel costs increase sharply or production gets delayed. Its profits may suffer, and its share price could fall even as gold becomes more valuable.
That makes gold mining ETFs a different investment from physically backed gold ETFs. GDXJ also brings greater business risk because smaller mining companies can be more vulnerable to financial and operational setbacks.
3. Individual Gold Mining Stocks: Newmont, Agnico Eagle and Barrick
Investors can also purchase shares of individual gold mining companies listed in the US.
Unlike a gold ETF, which follows the commodity, these stocks represent ownership in actual businesses. Their performance depends on how much gold they produce, what it costs to extract it and how profitably they operate.
| Gold Mining Stock | What Does the Company Do? | Important Risk |
| Newmont (NEM) | A major global gold producer operating mines across different regions. | Rising production costs, mine disruptions and operational setbacks can hurt earnings. |
| Agnico Eagle Mines (AEM) | A gold mining company with operations across several countries, including Canada. | Production volumes, mining expenses and execution of expansion projects affect profits. |
| Barrick Mining (B) | A global mining business producing gold and copper. | Along with gold prices, copper exposure, political risks and mine development costs influence performance. |
There is another important difference here. A gold mining ETF spreads investments across several companies, whereas buying a single mining stock puts more of your money behind one business.
If that company struggles with production, debt or unexpected costs, its share price can fall regardless of what happens to gold prices.
4. Leveraged Gold ETFs: UGL and NUGT
There is also a more aggressive category of US-listed gold products. These funds use financial contracts to magnify daily returns.
| Leveraged ETF | How Does It Work? | Annual Fee | Additional Risk |
| ProShares Ultra Gold (UGL) | Targets 2 times the daily movement of a gold futures index. | 0.95% | High risk. Gold futures movements are magnified, and returns can differ substantially from twice gold's return over longer periods. |
| Direxion Daily Gold Miners Bull 2X (NUGT) | Targets 2 times the daily movement of a gold mining stock index. | 1.13% | Very high risk. Combines mining company risks with daily leverage, potentially leading to sharp losses. |
For example, if UGL's benchmark rises 5% in a day, the fund aims to gain approximately 10% before expenses. But the reverse also applies. A 5% daily decline in the benchmark would mean an approximately 10% fall in the fund.
Importantly, these funds promise neither twice gold's return nor twice mining stocks' return over a full year. Their daily reset means that frequent ups and downs can significantly change the final result.
For Indian residents, access to these leveraged products also needs separate confirmation under applicable overseas investment rules. An ETF appearing on an investing platform does not automatically mean it is available or permissible to purchase.
For investors simply looking to add gold exposure to their portfolios, physically backed ETFs are the more direct comparison. Mining stocks introduce business risks, while leveraged ETFs are complex, higher-risk products that should not be treated as substitutes for a regular gold mutual fund SIP.
Indian Gold ETF vs US Gold ETF: Which Is More Practical?
A domestic ETF usually involves fewer steps for a ₹5,000 monthly investor: rupee funding, Indian trading and domestic records. A US gold trust may fit someone allocating an already-funded overseas balance.
Compare returns in the same currency
HDFC’s 27.41% INR return cannot be ranked directly against GLD’s 8.74% USD return: currency, pricing, valuation timing and costs differ.
Suppose an overseas investment gains 10% in dollars and the dollar appreciates 5% against the rupee. Ignoring costs, the INR return is 1.10 × 1.05 − 1 = 15.5%.
Domestic gold already reflects dollar gold prices and the exchange rate, alongside duties and local premiums. A US ETF changes the location, structure and costs of the investment; it does not automatically add an entirely new source of dollar-linked gold returns.
Compare the complete cost
GLDM’s 0.10% fee is lower than GLD’s 0.40%. On an average investment worth ₹1 lakh, that 0.30 percentage-point gap represents roughly ₹300 annually, before other differences.
Cross-border investing also involves forex, possible remittance charges, brokerage, spreads and withdrawal conversion. An illustrative 1% entry conversion cost is ₹1,000 on ₹1 lakh. Fixed charges especially affect small monthly remittances; check actual current tariffs.
Account for tax and reporting
For fresh investments, listed Indian gold ETFs generally qualify for 12.5% long-term capital-gains tax without indexation after more than 12 months; unlisted gold FoFs require more than 24 months. Shorter holdings generally face slab rates. Cess/surcharge apply, and the equity-fund ₹1.25 lakh exemption does not. Earlier transactions need separate review. See mutual fund taxation rules.
Ordinary US gold trusts treated as foreign capital assets generally require more than 24 months for India’s 12.5% long-term rate. US listing does not qualify as Indian listing. Foreign income, distributions and tax credits need separate consideration, especially for partnership products.
Investment remittances under LRS generally attract 20% TCS on the portion above ₹10 lakh in the financial year, after accounting for the applicable aggregate threshold. With no earlier relevant remittances, ₹12 lakh for investment implies ₹40,000 TCS on the excess ₹2 lakh. TCS is creditable against tax liability, with any eligible excess refundable through the tax-return process; it creates a cash-flow requirement rather than necessarily being a final investment tax.
Resident and ordinarily resident taxpayers must also report relevant foreign assets and income in the appropriate return schedules. US-situs holdings can create estate-tax issues: the IRS generally requires a nonresident noncitizen estate return above US$60,000 of US-situated assets, subject to its detailed rules. That threshold is aggregate and is not an automatic tax bill. Check each product’s legal structure and asset situs. [S29, S30]
What Should Gold Investors Do Now?
Start with your original investment goal.
| Your situation | Practical next step | Main limitation to check |
| My gold mutual fund SIP is running | Check whether its existing instalments qualify to continue | Registration cutoff, top-ups and consequences of cancelling |
| I planned a ₹1 lakh lump sum | Compare domestic gold ETFs and actual exchange quotes | Premium to current iNAV, spread, depth and total charges |
| I want to invest ₹5,000 monthly | Arrange regular ETF purchases manually or through supported scheduling | Funding, whole units, charges and execution; scheduling is not guaranteed allotment |
| I am considering an SGB or US gold trust | Evaluate the specific series or product against the domestic ETF route | SGB price, maturity and tax; overseas access, remittance and reporting |
| I want higher returns through miners or leverage | Reassess whether you want company or speculative trading exposure | Greater risk does not guarantee greater returns; daily objectives change outcomes |
Without a demat account, check whether a suitable pure-gold mutual fund accepts your transaction. Otherwise, assess opening the required account or waiting for a suitable route. Availability alone does not make another product suitable.
If gold was meant to diversify your portfolio, preserve that role. An inflow restriction does not require abandoning your goal or increasing risk to pursue it.